

www.ferroalloynet.com: Roundtable Dialogue invited industry representatives from manganese mines, manganese alloy plants, manganese silicon futures and spot research institutions, and downstream steel mills to engage in in-depth dialogue on the current operating status of the entire manganese industry chain, core contradictions, and market prospects for the fourth quarter. From the perspective of the front line of the industry, the forum reviewed the market changes since the beginning of this year, exchanged differences, and brainstormed ideas.
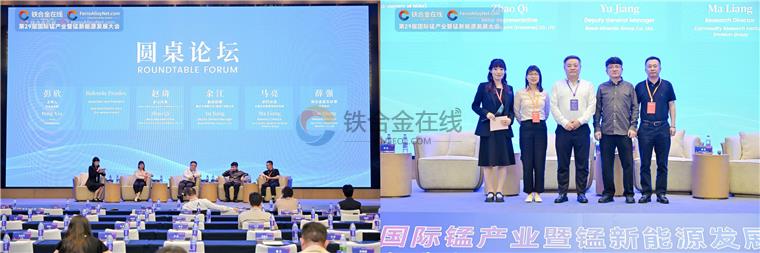
Upstream Mines: Rising Overseas Supply Costs and Transportation Bottlenecks Become Key Constraints
WMA mining representative Zhao Qi explained that the significant fluctuations in international oil prices this year have directly driven up production and shipping costs for overseas mines. Taking South African mines as an example, shipping costs have risen significantly since the beginning of the year, resulting in a substantial increase in logistics costs per ton of manganese ore. From the supply side, South African manganese ore production saw a slight increase from January to July, but limited rail capacity and heavy reliance on road transport mean that transportation remains the biggest bottleneck restricting shipment volume. Although mines have some potential for increased production, it is difficult to quickly overcome the logistics ceiling. It is expected that shipments of South African high-speed rail manganese ore will decrease in the fourth quarter, while shipments of semi-carbonate manganese ore are expected to remain high. Meanwhile, coupled with the continuous accumulation of port inventories, the interplay between international pricing, delivery schedules, and domestic demand is intensifying. Overall, overseas mine shipments in the fourth quarter are expected to remain stable with some changes.

Alloy Plants: High Inventory + Cost Squeeze Leads to Widespread Industry Losses and Increased Willingness to Reduce Production
Mr. Yu Jiang, Deputy General Manager of Bosai Mining Group Co., Ltd., shared the current state of the industry from the production side: The domestic manganese alloy industry is currently facing a predicament of high social inventory, weak demand, and inverted costs. National total manganese ore inventory and ferrosilicon alloy inventory are both at high levels, with total inventory equivalent to nearly two months of market consumption. This "double high inventory" is exerting strong downward pressure on spot prices, and the supply-demand imbalance is unlikely to reverse quickly in the short term. On the raw material side, coking coal and coke supply is tight, and prices continue to rise. Coal and coke costs have become a significant burden on alloy companies. Recent rounds of coke price increases have directly impacted ferrosilicon production costs, resulting in severely contracted profits and losses for most plants in both northern and southern regions.
Under these circumstances, investment in new capacity in the industry is generally cautious; companies are more inclined to digest existing social inventory first. Yu Jiang mentioned that in the face of the severe market conditions, some leading companies in the industry have already planned to proactively reduce production in the fourth quarter to cope with the current pressure by adjusting supply. He also called for attention to be paid to the optimization of relevant export and tariff policies in order to create conditions for the healthy development of the industry, given the industry's continued losses.
Futures and spot perspective: Basis spread game intensifies, two major risk points deserve attention, market may fluctuate weakly.
Mr. Ma Liang, Research Director of the Commodity Research Institute of Envision Group, interpreted the market from the perspectives of basis logic and macroeconomic risks: Under the overall environment of reduced demand, the ferrous metals market, including silicon manganese, exhibits a clear "involution" characteristic; in the long term, basis trends are highly correlated with price trends; in the short term, it is necessary to comprehensively judge basis fluctuations by combining production ranges, inventory levels, and the dynamics of enterprise shutdowns and restarts, rather than simply extrapolating linearly.
Two core risks in the fourth quarter: First, the structural tightness of coal and coke has not been fully resolved, and there is still upward pressure on costs; second, steel mill profits are at a low level, and cost pressures are not being effectively transmitted downwards. If steel mills are forced to reduce production, it will directly lead to a weakening of alloy demand.
In summary, silicon manganese is likely to maintain a weak and downward trend in the fourth quarter, with some cost support in the 5600-5900 yuan/ton range, mainly characterized by weak and narrow fluctuations. Meanwhile, with market expectations generally cautious, the entire industry chain's "willingness to replenish inventory has weakened significantly." Steel mills and traders are mostly purchasing on an as-needed basis, and it is difficult to see a large-scale, proactive, excessive replenishment of inventory. Futures trading has become an important reference for industry pricing, but the wide-ranging basis also brings considerable operational risks to real economy and trading companies.

Downstream steel mills: Profitability under pressure, procurement strategies are stabilizing, adhering to just-in-time and cautious restocking.
Mr. Xue Qiang, General Manager of the Ferroalloy Department of the Raw Material Procurement Center at Baoshan Iron & Steel Co., Ltd., shared the steel mills' real-world experience: Recently, raw material prices have risen significantly more than finished steel prices, drastically compressing the price difference between steel mills' purchases and sales. Many steel mills have fallen into losses again, and the industry is facing immense operational pressure. Looking ahead to the fourth quarter, after the traditional "Golden September and Silver October" peak season, the market will gradually enter the off-season; demand for different products (plates, long products, special steel, and ordinary products) will diverge; if steel mill output declines significantly, the demand impact on ordinary ferrosilicon alloys will be greater than that on some special alloys.
In terms of procurement strategy, Baosteel will adhere to a prudent approach, implementing procurement based on actual production needs; it will not pursue simply bargaining with suppliers for low prices, but rather hopes to establish long-term, stable, and win-win supply chain cooperation with high-quality ferrosilicon alloy producers, and welcomes qualified production enterprises to participate in the construction of the supply system.
Collective Outlook: Multiple perspectives with varying emphases, consensus and disagreements coexist
In the closing remarks of the roundtable discussion, several guests offered brief predictions for the manganese industry chain in the fourth quarter using key terms:
Mining: Stable with some changes
Production: Stable with some declines
Futures and Spot Research: Oscillating and bottoming out
Steel Mills: Slightly weak and volatile